Stock Analysis · Datatec Limited (DTTLY)
Overview
Datatec Limited is an international information and communications technology group focused on helping large organizations build, run, secure, and finance their IT infrastructure. Its activities span technology distribution, integration and managed services, and advisory work around networking, cybersecurity, cloud, and digital transformation. In practical terms, the company sits in the middle of the enterprise technology supply chain: it connects major hardware and software vendors with corporate and public-sector customers, while also providing specialist services around deployment, support, and lifecycle management.
The business is mainly organized around three operating areas: Westcon International, which distributes cybersecurity and networking products; Logicalis, which provides IT solutions and services; and Analysys Mason, a smaller consulting arm focused on telecom, media, and technology. Revenue is therefore broad-based across products and services, but distribution still accounts for a very large share of sales because that model passes through high volumes at relatively low margins.
Based on the group’s recent structure, the main sources of revenue appear to be roughly the following:
- Technology distribution through Westcon International: approximately 55% to 65% of group revenue.
- IT solutions, integration, and managed services through Logicalis: approximately 35% to 45% of group revenue.
- Consulting through Analysys Mason: well below 5% of group revenue.
That revenue mix matters because it explains both the scale and the limits of the business. Distribution can produce very large sales but usually thinner margins, while services and recurring support contracts tend to be more profitable and strategically valuable. Over the last few years, Datatec has kept expanding gross profit even while the headline revenue base changed materially, which suggests the company is moving toward a healthier mix rather than chasing volume alone.
The long-term pattern visible here is a business that has become smaller in reported revenue since 2024 but stronger in gross profit and net income. That usually points to a shift in mix, disposals, or tighter operational discipline rather than simple demand weakness.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Sep 12, 2026 | |
| Context | ||
| Sector | Technology | |
| Industry | Information Technology Services | |
| Market Cap ⓘ | $1.20B | |
| Beta ⓘ | -0.20 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 12.86 | 29.51 |
| FCF Yield ⓘ | 23.57% | 4.25% |
| EBIT / EV ⓘ | 34.49% | 2.85% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 3.80% | 15.40% |
| RPS Growth (5Y CAGR) ⓘ | 8.68% | 8.56% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -11.88% |
| Margin Growth (5Y Trend) ⓘ | 4.23% | 0.46% |
| FCF Growth (5Y CAGR) ⓘ | 64.56% | 9.80% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.44% |
| ROIC (5Y Median) ⓘ | 8.73% | 8.30% |
| Net Debt / EBIT (Latest) ⓘ | -0.00 | 0.54 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.85 | 0.44 |
| Operating Margin (Latest) ⓘ | 5.53% | 9.58% |
| Operating Margin (5Y Median) ⓘ | 2.66% | 8.25% |
| Debt to Equity (Latest) ⓘ | 130.06% | 33.33% |
| Profit Margin (Latest) ⓘ | 2.50% | 7.14% |
| Free Cash Flow (Latest) ⓘ | $283.08M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +194.99% | +45.48% |
| 12M Return (excl. last month) ⓘ | +53.76% | +23.48% |
| 6M Return ⓘ | 0.00% | +20.93% |
| Price vs. 200-Day MA ⓘ | +58.49% | +7.43% |
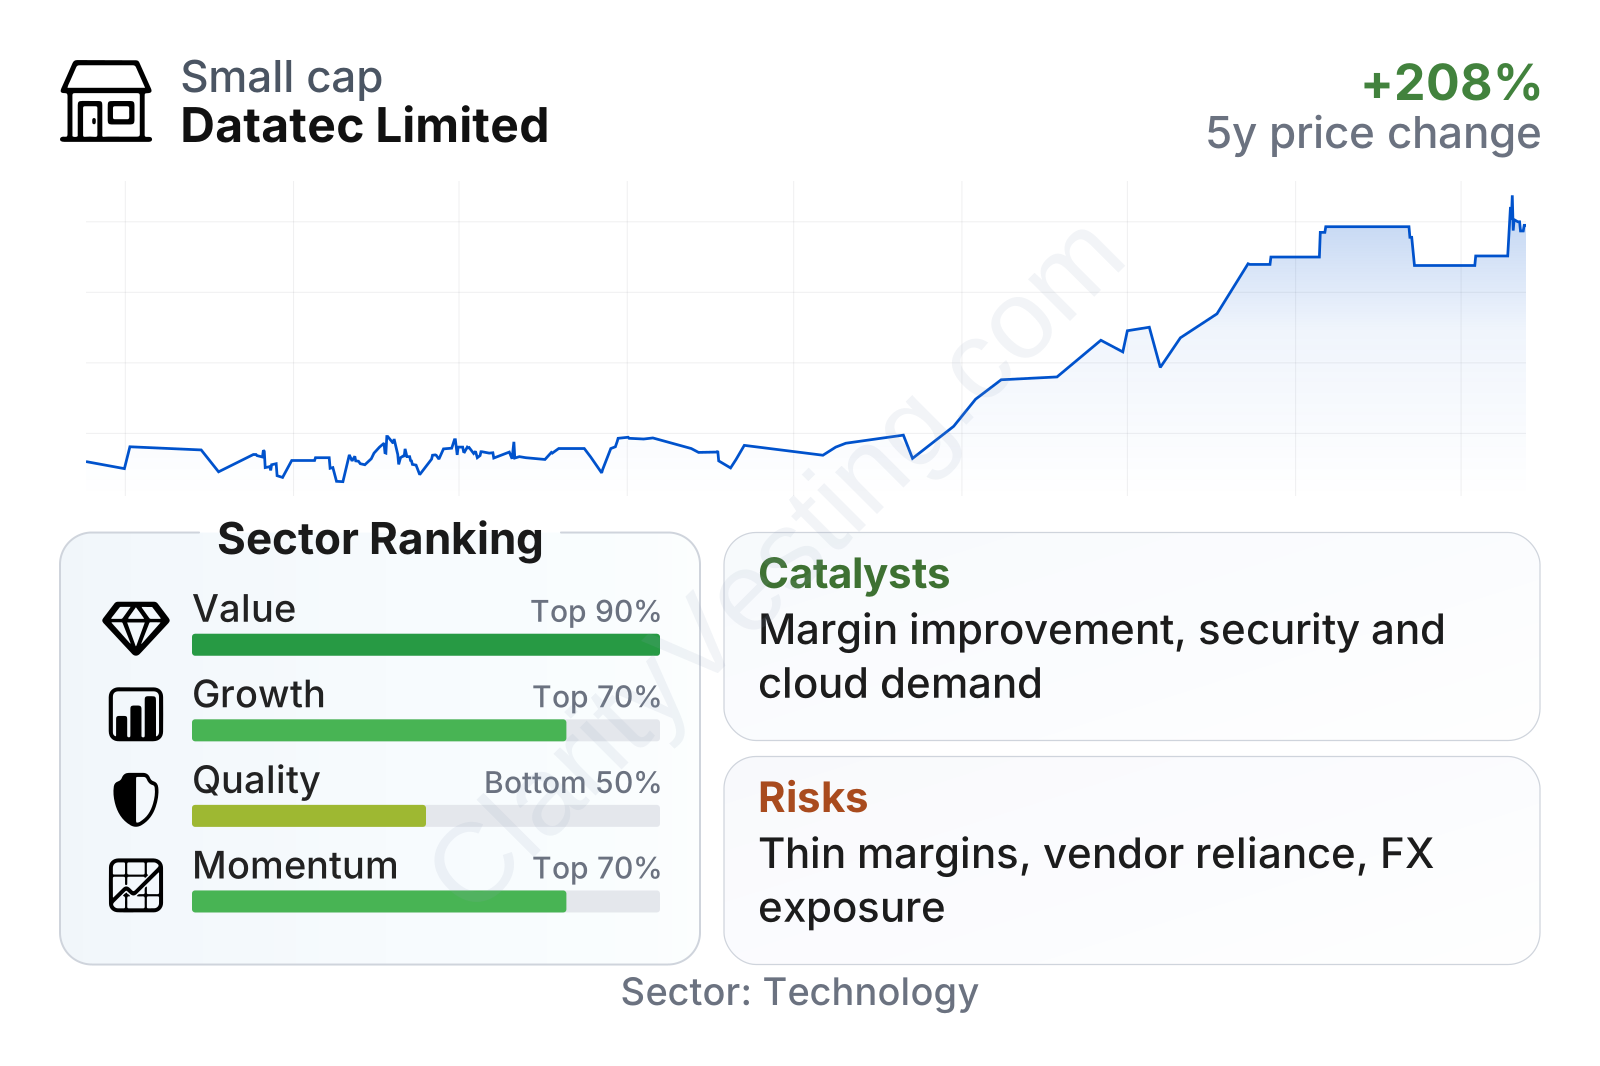
Datatec currently combines a mid-sized market value with unusually strong cash-generation metrics relative to much of the technology services sector. Its value indicators look favorable, with earnings and cash flow multiples sitting well below sector norms, while momentum remains solid over multi-year and trailing twelve-month periods. The weaker side of the profile is growth and operating quality: sales growth has been modest, profitability remains below the sector median, and returns on invested capital appear less impressive than many peers. In short, the market is recognizing improving fundamentals, but the company still screens more like a cash-generative operator than a high-growth technology name.
Growth
Datatec operates in parts of the technology market that still have durable structural demand. Cloud migration, cybersecurity, hybrid infrastructure, network modernization, data-center refresh cycles, and AI-related enterprise spending all require the kind of vendor relationships, integration expertise, and support capabilities that the group provides. This does not make Datatec a pure-play on the fastest-growing software themes, but it does place the company in a segment that benefits when enterprises continue modernizing critical systems.
The strategic logic is fairly clear. Westcon gives Datatec reach into fast-moving vendor ecosystems, especially in security and networking, while Logicalis can capture higher-value work by designing, implementing, and managing technology environments for customers. That combination can be useful because it links product access with ongoing services. If executed well, it can deepen customer relationships and reduce dependence on one-off hardware cycles.
Near-term growth, however, looks steady rather than explosive. Recent year-over-year revenue expansion has been positive but slower than the sector median. That supports a balanced view: Datatec is exposed to attractive demand areas, but its group profile does not currently resemble a rapid-growth software platform. A more encouraging sign is that margin trends have improved over a multi-year period, which means future progress does not need to come only from higher sales.
Cash flow is one of the more constructive parts of the picture. Free cash flow has strengthened sharply over time, and the latest level is meaningful relative to the company’s size. For a business in distribution and services, that matters because strong cash conversion can support balance-sheet flexibility, investment capacity, and shareholder returns even when revenue growth is moderate.
One notable recent development is the continued improvement in full-year profitability through the February 2026 fiscal period, with net income moving higher and interest expense easing from the prior year. That combination points to a business that may be getting more efficient at a time when enterprise technology budgets remain resilient in areas such as security, networking, and managed services. The strongest catalyst is therefore not a single headline event, but the possibility that better mix and execution continue lifting earnings faster than revenue.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


