Stock Analysis · Core Scientific Inc (CORZ)
Overview
Core Scientific Inc is a digital infrastructure company best known for operating large data centers that support high-performance computing. Historically, the business was centered on Bitcoin mining, both for its own account and for customers that placed their machines in Core Scientific facilities. More recently, the company has been repositioning part of its infrastructure toward artificial intelligence and other high-performance computing workloads, which broadens its business beyond cryptocurrency.
The company’s revenue mix has changed over time, but the main sources of revenue generally come from a small number of activities tied to its data center platform.
- Self-mining: revenue from Bitcoin mined using machines owned and operated by Core Scientific. This has often been the largest contributor and can represent roughly 40% to 60% of revenue depending on Bitcoin prices, network difficulty, and machine uptime.
- Hosted mining / colocation: revenue from providing power, space, operations, and support for third-party mining customers. This has typically represented about 20% to 40% of revenue, though it can move meaningfully as contracts begin, expire, or get restructured.
- Digital asset sales and related services: revenue linked to selling mined Bitcoin and certain ancillary data center services. This is usually a smaller share and can vary materially by period.
- High-performance computing hosting: a newer source tied to infrastructure leased for AI and similar computing uses. Today this is still emerging, but strategically it is becoming more important than its current share suggests.
In practical terms, Core Scientific owns and runs power-dense facilities, then monetizes that infrastructure either by mining Bitcoin itself or by renting capacity to outside customers. That means its economics depend heavily on electricity costs, equipment efficiency, facility utilization, and the market value of the workloads running on its sites.
The long-term financial picture has been uneven. Revenue recovered at points, but profitability has remained weak, reflecting both the volatility of Bitcoin economics and the heavy cost structure of maintaining large-scale infrastructure. One notable pattern over the last several years is that financing costs have come down, but operating losses have still remained substantial.
The historical flow of revenue and costs shows a business that can generate meaningful gross profit in better periods, but has struggled to convert that into durable operating earnings. Interest expense has improved markedly from earlier stressed years, yet selling, administrative, and other operating costs have continued to weigh heavily on results.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 10, 2026 | |
| Context | ||
| Sector | Technology | |
| Industry | Software - Infrastructure | |
| Market Cap ⓘ | $5.33B | |
| Beta ⓘ | 5.48 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 30.74 |
| FCF Yield ⓘ | -18.14% | 4.05% |
| Dividend Yield ⓘ | N/A | 1.29% |
| EBIT / EV ⓘ | -16.81% | 2.81% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 108.80% | 15.80% |
| RPS Growth (5Y CAGR) ⓘ | -19.03% | 8.56% |
| EPS Growth (5Y CAGR) ⓘ | -61.12% | -11.61% |
| Margin Growth (5Y Trend) ⓘ | N/A | 0.49% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 9.80% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 7.74% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -157.59% | 9.39% |
| ROIC (5Y Median) ⓘ | N/A | 8.35% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 0.50 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 0.51 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 0.28 |
| Net Debt / Assets ⓘ | 48.09% | 3.46% |
| EBITDA / Interest ⓘ | N/A | 13.31 |
| Operating Margin (Latest) ⓘ | -318.56% | 9.77% |
| Operating Margin (5Y Median) ⓘ | -90.29% | 8.53% |
| Debt to Equity (Latest) ⓘ | -177.65% | 34.80% |
| Profit Margin (Latest) ⓘ | N/A | 7.13% |
| Free Cash Flow (Latest) ⓘ | -$967.87M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | N/A | +54.57% |
| 12M Return (excl. last month) ⓘ | +31.35% | +16.76% |
| 6M Return ⓘ | +2.39% | +22.43% |
| Price vs. 200-Day MA ⓘ | -15.83% | +8.85% |
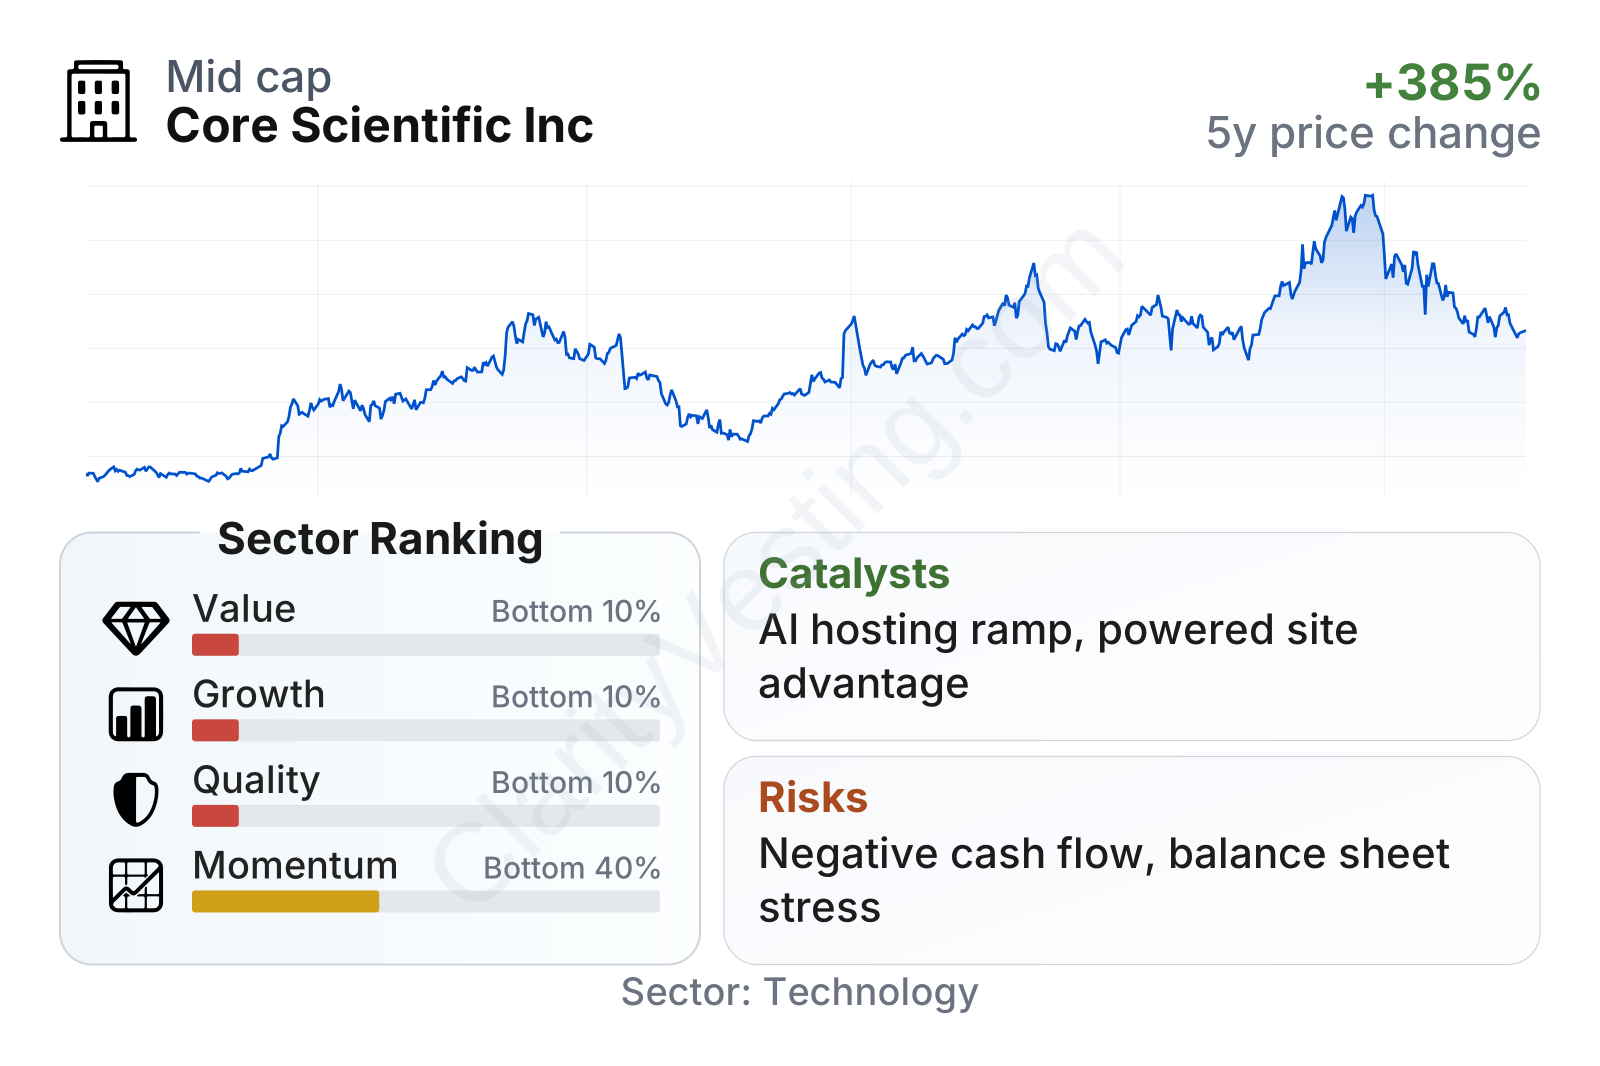
Core Scientific is now a mid-sized public company by market value, but its stock remains highly volatile, with a beta above 5. That is unusually high even in a speculative part of the technology market and helps explain why the share price has moved sharply over a relatively short period. The stock’s longer move has been strong since early 2024, but the more recent trend looks less decisive, with trading below the 200-day average despite gains over the prior year.
The factor summary points to a mixed setup. Revenue growth has recently accelerated far above the sector median, yet quality, value, and profitability metrics remain near the bottom of the technology group. Negative free cash flow, negative operating returns, and weak balance-sheet signals suggest that headline growth should be read alongside unusually high execution and financing risk.
Growth
Core Scientific operates in areas that can grow quickly, but they are not equally reliable. Bitcoin mining can expand rapidly when digital asset prices are favorable, yet it remains cyclical and difficult to forecast because rewards, energy costs, and network competition change constantly. By contrast, high-performance computing infrastructure has a more conventional long-term demand profile, especially as AI training and inference require large amounts of power and specialized data center capacity. That second market is one of the company’s most important strategic opportunities.
The company’s strategy makes sense on paper because it builds on assets it already owns: large sites, power access, and experience running dense compute environments. Instead of relying only on Bitcoin economics, Core Scientific is trying to reposition parts of its platform toward workloads that may produce longer-duration contracts and potentially better visibility. This is especially relevant because demand for power-ready compute space has become one of the key bottlenecks in the AI infrastructure market.
Recent revenue growth has turned sharply positive after a period of steep declines. That rebound is encouraging because it shows the business is capable of recovering from a weak base, but it does not yet erase the wider history of inconsistent sales performance. Over a multi-year period, revenue per share still looks weak, which means recent momentum must continue for the turnaround case to become more convincing.
Cash generation remains the main gap in the growth narrative. Free cash flow has become more negative rather than less, indicating that expansion and repositioning still consume heavy capital. For a capital-intensive operator, this matters as much as revenue growth because data center opportunities only become more valuable if they can eventually translate into durable cash production.
A major recent catalyst has been the company’s push into AI-related hosting through long-term infrastructure arrangements. Public company disclosures and investor communications have highlighted agreements tied to converting significant capacity for high-performance computing use. If those projects ramp as planned, they could diversify revenue away from a pure Bitcoin cycle and change how the market values the business. That is likely the clearest strategic opportunity currently visible.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


