Stock Analysis · Acm Research Inc (ACMR)
Overview
ACM Research, Inc. designs and sells equipment used in semiconductor manufacturing. In simple terms, its machines help chipmakers clean, process, package, and inspect wafers during production. The company is best known for wet cleaning tools, which are used to remove particles and contamination from wafers, but it has expanded into other steps of the chip production flow as well. ACM Research operates in a part of the semiconductor industry that benefits when chip manufacturers add capacity, improve yields, or move to more advanced production methods.
The business is primarily equipment-driven, with additional recurring activity from support and spare parts. Based on the company’s recent annual disclosures, revenue is concentrated in a few main buckets:
- Single-wafer cleaning, bevel etch, and related wet processing tools: the largest revenue source, estimated at more than 50% of total revenue. These tools are central to ACMR’s positioning and are used in wafer cleaning and surface treatment.
- Electro-chemical plating, track, furnace, packaging, and other front-end/back-end tools: estimated at 25% to 40% of revenue. This category reflects the company’s broader push beyond its original cleaning niche.
- Services, spare parts, and other support revenue: estimated at 5% to 15% of revenue. This includes maintenance-related activity and customer support tied to installed equipment.
Geographically, ACM Research has historically generated the great majority of its revenue in China through semiconductor manufacturers expanding local capacity. That concentration has been a major growth engine, but it also makes the company more exposed to policy and trade restrictions than many larger global peers.
The business mix also shows a company still investing for scale. Revenue has risen sharply over the last several years, while research and development spending has also climbed, which suggests management is trying to turn a successful niche product line into a broader semiconductor equipment platform.
The longer-term financial flow shows strong top-line expansion from 2021 through 2025, with research and development spending rising materially along the way. Gross profit has grown in absolute dollars, but profitability did not increase as smoothly in 2025, which points to a business still balancing expansion, product breadth, and execution.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Sep 12, 2026 | |
| Context | ||
| Sector | Technology | |
| Industry | Semiconductor Equipment & Materials | |
| Market Cap ⓘ | $5.04B | |
| Beta ⓘ | 1.95 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 34.80 | 29.51 |
| FCF Yield ⓘ | -2.38% | 4.25% |
| EBIT / EV ⓘ | 6.15% | 2.85% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 36.00% | 15.40% |
| RPS Growth (5Y CAGR) ⓘ | 35.48% | 8.56% |
| EPS Growth (5Y CAGR) ⓘ | 1.37% | -11.88% |
| Margin Growth (5Y Trend) ⓘ | -1.10% | 0.46% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 9.80% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 11.37% | 9.44% |
| ROIC (5Y Median) ⓘ | 9.73% | 8.30% |
| Net Debt / EBIT (Latest) ⓘ | -2.64 | 0.54 |
| Net Debt / EBIT (5Y Median) ⓘ | -2.44 | 0.44 |
| Operating Margin (Latest) ⓘ | 23.44% | 9.58% |
| Operating Margin (5Y Median) ⓘ | 17.75% | 8.25% |
| Debt to Equity (Latest) ⓘ | 18.78% | 33.33% |
| Profit Margin (Latest) ⓘ | 14.48% | 7.14% |
| Free Cash Flow (Latest) ⓘ | -$120.13M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +304.84% | +45.48% |
| 12M Return (excl. last month) ⓘ | +225.95% | +23.48% |
| 6M Return ⓘ | +59.05% | +20.93% |
| Price vs. 200-Day MA ⓘ | +12.30% | +7.43% |
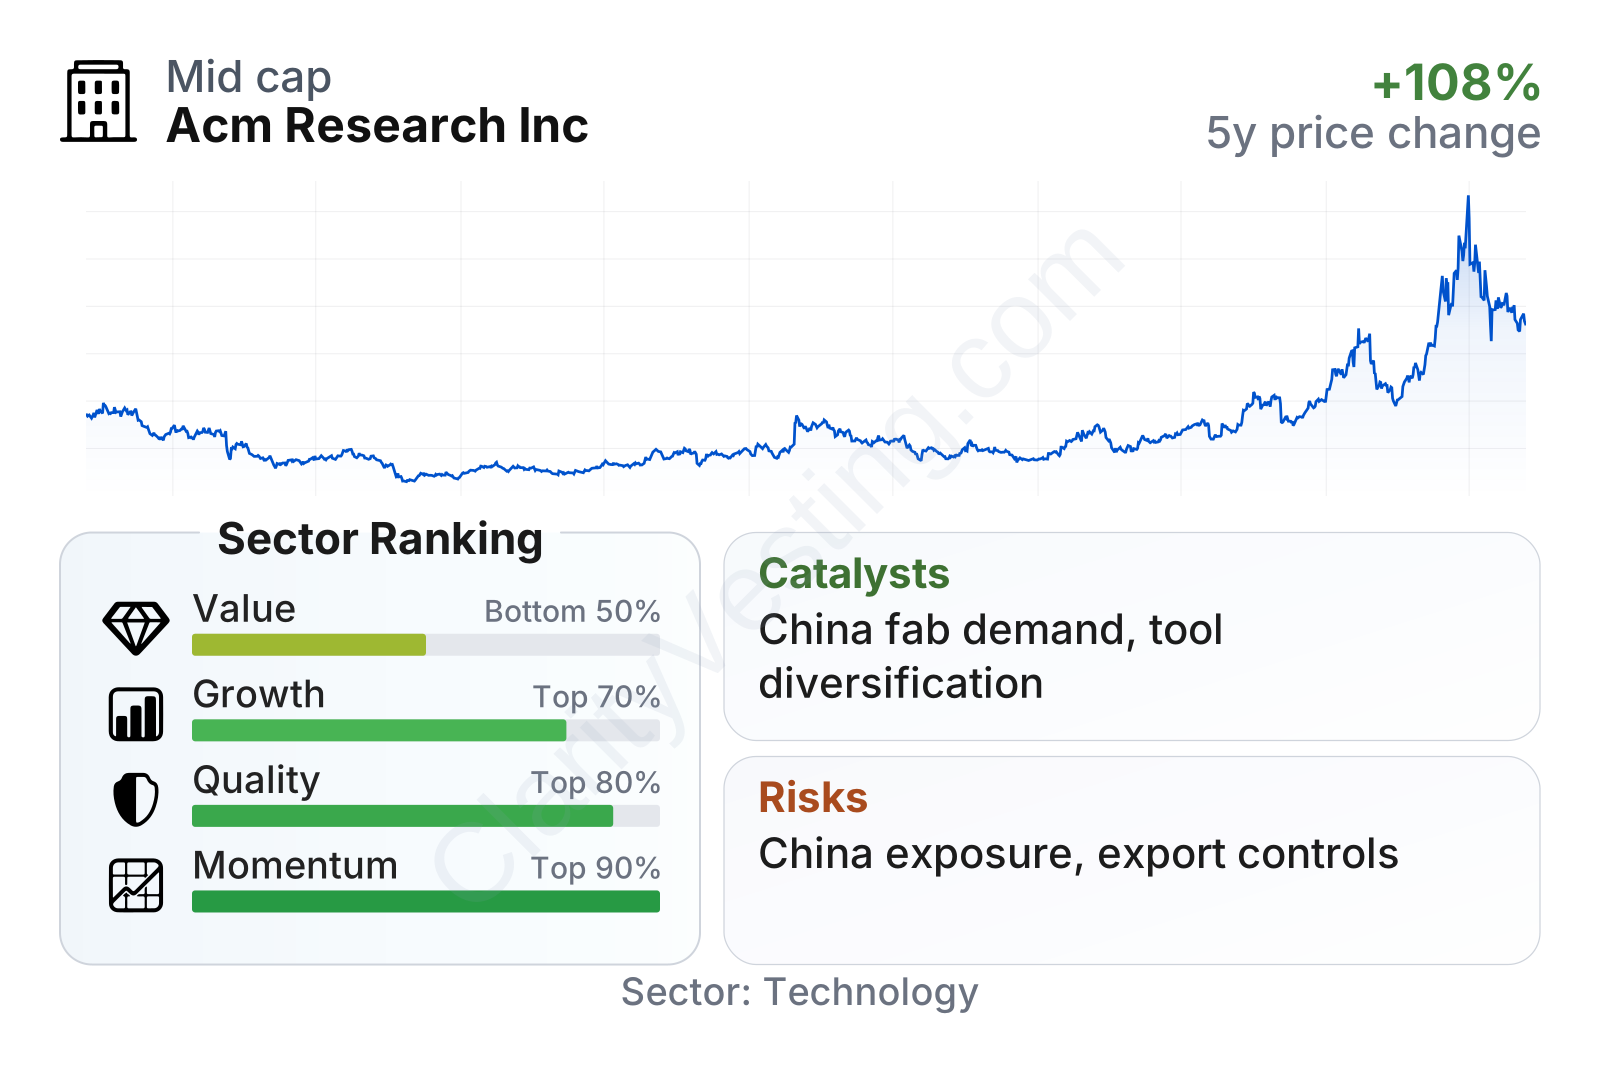
ACM Research is now a mid-sized semiconductor equipment company with a stock that has been very volatile. On the factor breakdown, growth, quality, and momentum look stronger than much of the sector, while value looks less attractive. Profitability remains better than the industry median, leverage is relatively low, and returns on invested capital are solid. The weaker point in the current snapshot is cash generation, with free cash flow still negative over the trailing twelve months despite strong revenue growth.
The stock price history reflects that mixed profile. Over the last few years, the shares moved through a deep downturn and then a sharp rebound, ending far above earlier levels. That pattern usually signals two things at once: the market recognizes meaningful business progress, but it is also assigning a higher level of uncertainty to future results.
Growth
ACM Research operates in a structurally growing market. Semiconductor manufacturing equipment benefits from long-term demand for chips in data centers, artificial intelligence, electric vehicles, smartphones, industrial automation, and connected devices. Even though the industry moves in cycles, the broad direction has been upward because more computing power requires more advanced and more numerous chips.
ACM Research’s strategy for future growth is fairly easy to understand. It is trying to deepen its position in cleaning equipment, where it already has proven customer adoption, and then use those relationships to sell a broader set of tools. That approach makes strategic sense because semiconductor manufacturers prefer equipment vendors that can solve several process steps rather than just one isolated need. If ACMR can keep expanding from cleaning into plating, track, furnace, and advanced packaging applications, its addressable market becomes much larger.
Revenue growth has been strong but uneven, which is normal in semiconductor equipment. Recent year-over-year growth has re-accelerated into the mid-30% range, well above the sector median. Over a five-year view, revenue per share growth has also been far stronger than the industry midpoint, indicating that the company’s expansion has not simply come from financial engineering.
The main caution within the growth picture is cash conversion. Free cash flow has swung between negative and positive territory and is currently negative again. For a company selling capital equipment, this can happen when inventory, receivables, manufacturing capacity, or customer timing absorb cash. It does not automatically undermine the growth case, but it does mean the business still looks more like a scaling company than a mature cash machine.
Several catalysts could matter over the next few years. The first is continued semiconductor investment in China, where ACM Research already has a strong customer base. The second is broader adoption of advanced packaging and process-intensity trends, which create more cleaning and deposition steps per wafer. The third is product diversification: each successful addition outside the core cleaning segment can increase both revenue opportunities and customer stickiness.
Recent company updates have also emphasized new tool qualifications, customer expansion, and production capacity development. Those are not guaranteed revenue immediately, but in semiconductor equipment they are often important milestones because customers typically require long testing and qualification cycles before placing larger orders.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


